Independent agency · Licensed in 48 states

Asphalt Contractor Insurance

Sealcoating, paving and parking-lot striping are three different risks that arrive on one account. We place all three, in every state we are licensed in, with markets that write the class on purpose.

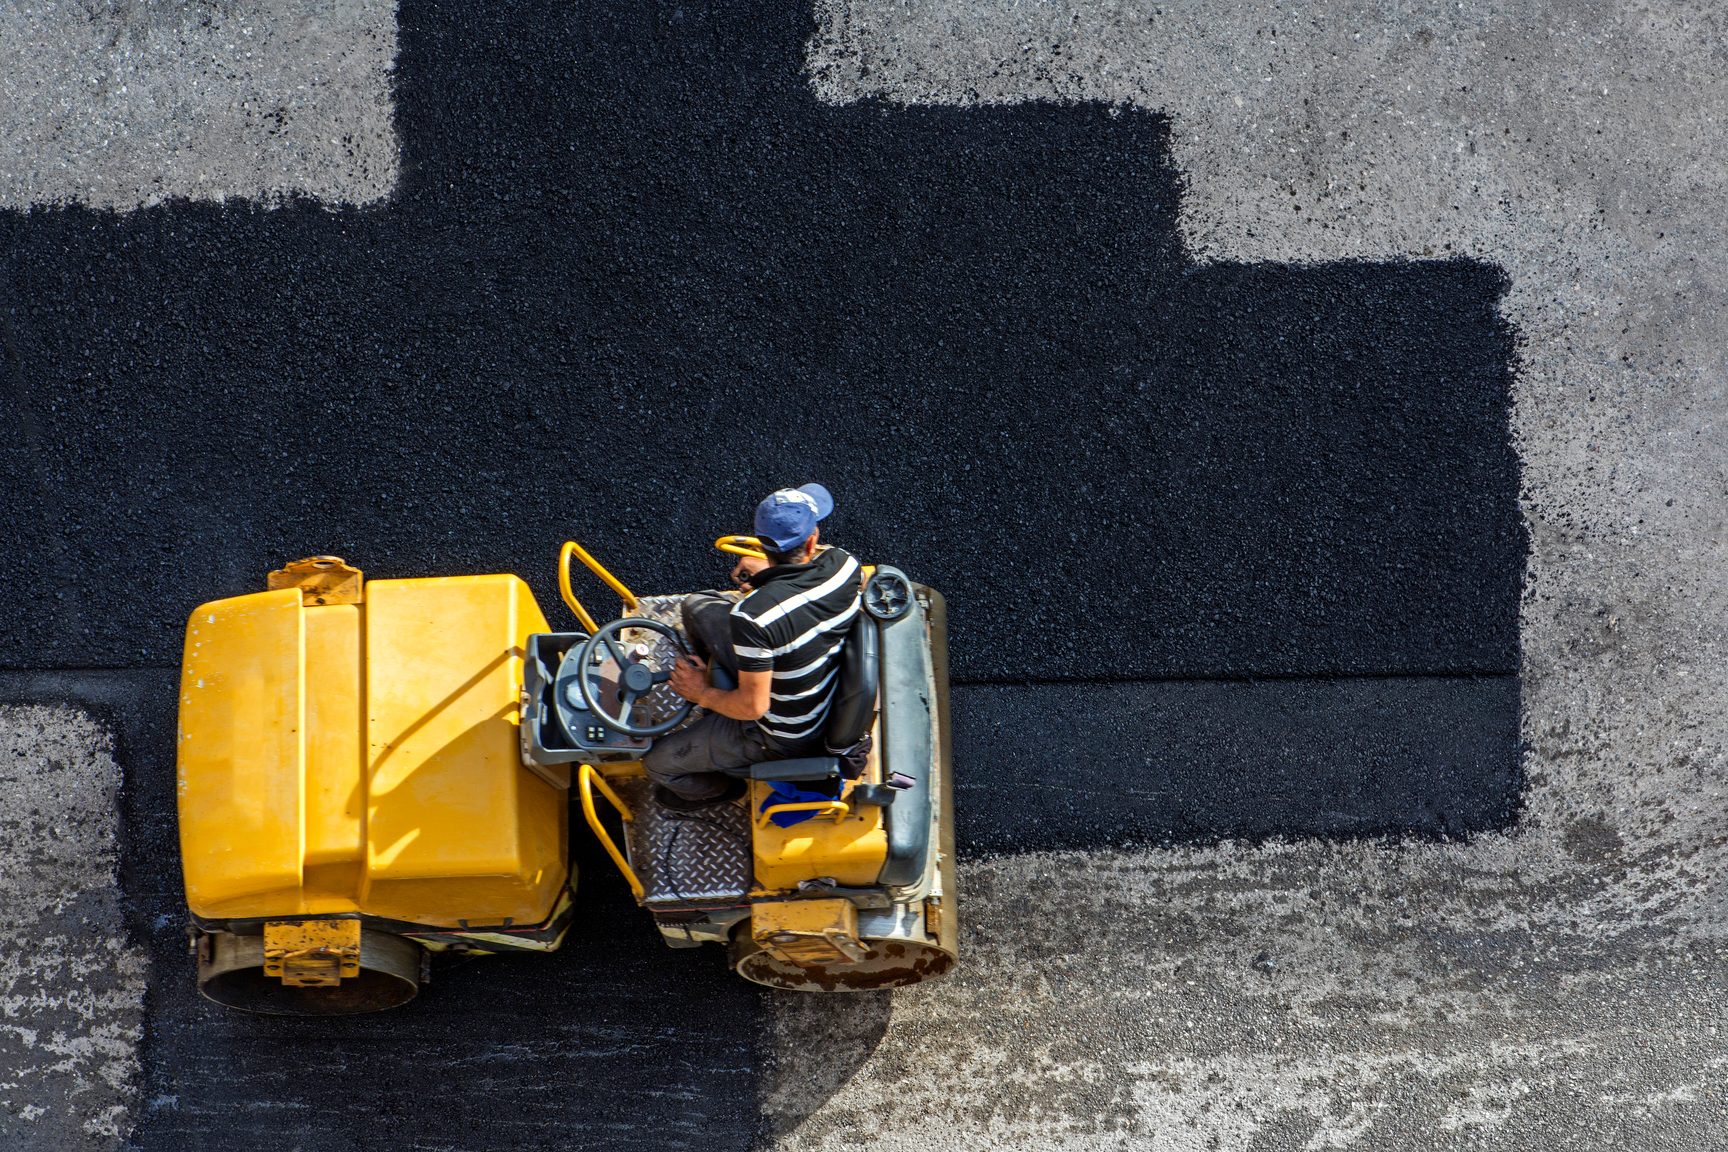
Overhead view of an operator on a yellow tandem roller compacting a fresh section of hot-mix asphalt over older gray pavement.
100+ Asphalt Contractors Insured
48 States Licensed
18 Specialty Markets
6 Core Coverages

Who we insure

Three kinds of work, and an underwriter reads them differently.

Hot-applied product and overspray

Sealcoating

Sealer goes down as a liquid and does not care what it lands on. The claims that follow a sealcoating crew are usually about somebody else’s property — a car on the next row, a storefront glass line, a lawn at the edge of the lot — and about the product being hot when it got there.

Completed operations and equipment on public ways

Paving

A paved surface is used by the public long after the crew leaves, so the exposure does not end at demobilization. Add a paver, a roller and a milling machine moving between a yard and a job on roads the public is also using, and two very different kinds of loss sit on one account.

Lot closures and work beside live traffic

Striping

Striping puts people on foot next to moving vehicles, often at night and often in a lot that is only partly closed. The work is short, the setup is everything, and the questions an underwriter asks are about traffic control rather than about paint.

What an asphalt program is made of

Six coverages, in the order they usually matter on this class.

General Liability

third-party bodily injury and property damage arising from work on and around a surface the public uses.

This form answers for what the machine does to somebody else — and it stops treating a paver as covered property the moment the question becomes damage to the paver itself.

Contractors Equipment

pavers, rollers, milling machines, sealcoat tanks and striping rigs — owned, rented and in transit.

This is where the paver, the roller and the milling machine are insured for their own damage, which is the exact thing the liability form declines to do.

Commercial Auto

dump trucks, tack trucks and equipment trailers on the road and at the jobsite.

Property

the yard, the shop, stored material and the plant the contractor owns rather than the one they buy from.

Professional Liability

specification, grade, drainage and mix-design decisions a contractor is paid to get right.

Guides for paving contractors

Questions contractors actually ask

Do you write sealcoating, or only paving?

Both, and striping as well. Most of the accounts we see do more than one of the three, and the mix matters — a crew that seals and stripes is underwritten differently from one that only lays mat.

My crews work on roads the public is still using. Is that a problem?

It is the normal condition of this trade, not a disqualifier. What underwriters want to see is how you set up traffic control and who is responsible for it on a given job.

Is my paver covered under my liability policy?

Not for its own damage. A liability form responds when your equipment injures someone or damages their property; damage to the machine itself belongs on a contractors equipment policy. That seam is the most common gap we find.

Do you cover equipment I rent for a single job?

Rented and borrowed equipment is a standard question on this class and is usually handled on the same policy as your owned machines, but the limit has to be set deliberately rather than assumed.

What about work I have already finished?

That is completed operations, and for a paving contractor it is not a footnote — a surface you laid is in use by the public for years. It is one of the first things we look at on a submission.

I only run in one state. Do I need to talk to a national agency?

You do not need to, but licensing, prequalification and sealant rules differ by state, and an agency that places this class in every state it is licensed in has usually already read yours.

How do you decide which market sees my account?

By where the appetite is for your state, your payroll, your equipment and your loss history. Appetite is not the same everywhere and it moves, which is why the panel is reviewed rather than fixed.

What do you need from me to start?

What you run, where you run it, and what has gone wrong before. A licensed agent reads the submission — there is no form that decides this for you.

Who we are, and how we place this class

Asphalt Contractor Insurance is a brand of Wexford Insurance, LLC, an independent agency licensed in 48 states. Independent means no single carrier owns the answer — we place the account where the appetite is, and on this class the appetite moves with the state and the work mix.

Our asphalt-contractor panel is 18 markets we hold appointments with, all quoting the class today:

Travelers Insurance, Liberty Mutual Insurance, UFG Insurance, Encova Insurance, The Hartford, West Bend Insurance, AMERISAFE, Cincinnati Insurance, Frank Winston Crum Insurance, GEICO, Progressive Commercial, Grand River Insurance, Hastings Insurance, Markel, Ohio Mutual Insurance, Pie Insurance, SECURA Insurance and Texas Mutual.

That list is reviewed quarterly and adjusted when a carrier’s appetite shifts. Which of them will look at your account depends on the state, the payroll, the equipment and the loss history — appetite is not the same everywhere, and we do not pretend it is.

Most of the paving owners I talk to have never been asked how their crews set up around live traffic. They have been asked their payroll and their receipts. The setup is the part that decides whether a bad day becomes a claim, and it is the part I want to hear about first.

— Nate Jones, CPCU, Founder

Wexford Insurance, LLC is a licensed independent insurance agency, NPN 19887690. You can verify our licensing at NIPR.com.

Tell us what you run and where you run it

A licensed agent reads every submission and comes back with what the markets will do.